OpEx and CapEx tracking basics can help reduce your company’s bottom line, balance project budgets, and identify cost-cutting opportunities.
Understand how capital and operational expenses differ, how each shapes your tax bill and balance sheet, and how to balance both inside Jira.
Key Takeaways
CapEx funds long-term assets that depreciate over years, while OpEx covers daily costs deducted in the same fiscal year.
The category you pick changes your tax bill, cash flow, balance sheet, and how investors read your company's growth story.
Most projects mix both: Hardware and licenses on the CapEx side, payroll, utilities, and subscriptions on the OpEx side.
Track both in real time inside Jira with Tempo Financial Manager and Structure PPM so finance and delivery see the same numbers.
Capital expenditures (CapEx) are large, long-term purchases that benefit the business for more than one year and get depreciated over the asset's useful life. Operational expenditures (OpEx) are recurring day-to-day costs – payroll, rent, utilities, software subscriptions – that get expensed in the year they're incurred.
Project expenses tend to land in both CapEx and OpEx categories. How you split them out matters, because each type follows a different approval path, lands on a different financial statement, and tells investors a different story about how the company is being run.
Companies track both buckets to keep the books honest and make sharper budget decisions. You can quickly surface savings – especially on technology – by tightening up how you classify and report CapEx and OpEx expenditures. Flexera's 2026 State of the Cloud report has named cloud cost optimization as the top challenge for enterprise IT leaders across recent annual editions, a reminder that the OpEx column is now where most discretionary tech spend hides.
This is especially true with the explosion of generative AI; because most teams rely on usage-based LLM APIs and cloud GPU infrastructure, AI boom cycles are inflating the operational budget rather than traditional capital reserves.
CapEx refers to significant, long-term projects or expenditures that, once implemented, improve an organization's fiscal performance, production capacity, or project quality. Unlike operating expenses, companies cannot deduct CapEx in the year spent; instead, they depreciate or amortize the cost over the asset's useful life.
These costs usually involve periodic, fixed spending on tangible assets like plant, property, and equipment (PP&E).
Capital expenses typically provide economic utility for longer than one fiscal year and are often the largest single line items a company commits to. The assets you buy represent your core business strategy and support long-term growth.
Typical CapEx expenditures include:
Manufacturing equipment
Facility additions and upgrades
Computer and network equipment
Company vehicles
Heavy equipment and machinery
Capitalized software development and major IT infrastructure
For a deeper look at how teams handle the project-level side of this, see Tempo's guide to CapEx tracking in Jira.
OpEx covers all the recurring day-to-day spending required to keep a company functioning. These are the costs of doing business – the line items that help the organization manufacture goods, offer services, or attract customers. The benefits from these expenses are near-term, meaning you feel the impact of the OpEx budget within a fiscal year. Because they're tied to the current year's operations, these costs are usually fully deductible in the same fiscal year, immediately reducing taxable income.
Common OpEx expenses include:
Property or facility rent
Utilities
Payroll and salaries
Overhead costs
Property taxes
Research and development (R&D)
SaaS subscriptions and cloud hosting fees
Generative AI enterprise subscriptions and usage-based API token fees (LLM inference costs)
Note that under US GAAP (ASC 730) R&D is treated as OpEx, while under IFRS (IAS 38) research costs are OpEx but development costs can be capitalized as CapEx if they meet strict recognition criteria.
The shift to subscription software and cloud services has pushed a meaningful share of what used to be CapEx (servers, perpetual licenses) into the OpEx column. That matters when you're reading old benchmarks: A company that looks "asset-light" today may simply be paying for the same capabilities monthly.
It's not always simple to delineate between capital expenditures and operating expenses, but the two have very different impacts on budgeting, reporting, and cash flow. Here are seven crucial differences:
While both expenditures improve a company's operations, they differ in the scope of their impact. OpEx spending covers the daily, weekly, monthly, and annual expenses that keep the lights on and the doors open. CapEx spending involves large costs expected to impact the organization's long-term capacity and profitability.
A CapEx expenditure incurs an upfront payment, usually from a fund dedicated to PP&E purchases. OpEx items recur, so you'll generally pay them weekly, monthly, or annually.
Because of their size and the high initial disbursement, companies treat CapEx projects as high-stakes decisions they can't reverse. Before committing, CapEx planning requires rigorous business case development, research, and analysis, plus multiple levels of individual and panel approvals.
OpEx spending is a recognized business necessity affecting only the short term, so it rarely needs the same approval gauntlet. Managers usually review operating expenses at year-end to forecast next year's budget and flag any spending outside the historical norm.
Companies typically purchase a CapEx asset outright, so teams control its operation and maintenance. That ownership lets them customize equipment to suit their needs, and if there's an in-house team handling upkeep, the company can reduce the operating cost by not contracting out to a third party. If a company leases technology or property as an OpEx expense, it gives up that control but also avoids the service and support burden.
How accounting handles capital versus operating expenses is the biggest difference between the two. CapEx projects aren't tax deductible in the year spent and are included in the company's cash flow statement for the period the team expensed the cost.
If the newly acquired asset is tangible (like a new piece of equipment), its value depreciates over time. The company can claim the depreciated value after a waiting period as a tax deduction. If the asset is intangible (like a patent or license), the cost is amortized over the asset's economic life cycle. Amortization is deductible, reducing the company's overall tax liability.
Accounting strictly tracks asset purchase and depreciation, giving stakeholders and investors a clear picture of the organization's financial well-being. OpEx items get deducted during the period incurred, with teams expensing these items and including them on the income statement.
Companies fund capital and operational expenses differently, creating a dedicated pool to finance CapEx projects and using general funds for OpEx items.
Because CapEx projects involve a significant initial investment, companies typically approve only a few initiatives a year. CapEx budgeting usually means:
Creating a separate capital expenditure budget
Soliciting input at the departmental and organizational level
Setting a budget limit
Assessing every CapEx project's potential return on investment (ROI)
Companies build an operations budget by reviewing historical budgeting data and adjusting for inflation, creating a forecasted cost for the upcoming year. This information provides insight into projected revenue and profit for the next quarter or year.
Budgeting for OpEx items includes:
Historical trend analysis
Market trend analysis
Inflation rate review
For teams that want a repeatable model, Tempo's guide to project budget tracking walks through how to combine historical data, real-time spend, and milestone tracking inside Jira.
CapEx and OpEx give investors different perspectives on a company's financial health. Comparing CapEx to operating cash ratios lets stakeholders see how much money a company dedicates to capital expenditures. A high ratio reflects significant growth objectives, while a lower value suggests the company has matured.
OpEx analysis helps investors understand how an organization distributes its budget and allocates funds. Comparing OpEx against net sales showcases management effectiveness, providing insight into sales performance and revenue.
Some projects involve both CapEx and OpEx items. If a company establishes a data center, the building, networking infrastructure, and office equipment are capital expenditures. But the money it spends on office supplies, utilities, and coffee and snacks counts as operating costs.
Most companies budget for both, but it can be hard to choose which to prioritize for a given project or company goal. A few things to weigh when deciding:
Financial strength: Owning capital assets means you don't have to keep paying for valuable equipment, which can improve your business's financial position.
Taxes: As an asset's value decreases over time, it produces a tax benefit when you claim it as a depreciation expense at year-end.
Investors: Reporting capital assets on the balance sheet signals higher profit and asset value to investors and other key stakeholders.
Potential losses: A company can't replace or walk back a capital investment without incurring significant losses. If you expect substantial growth or technological change in the coming years, an OpEx option is often safer.
Costs: Because of the upfront investment, CapEx projects require accurate projections, careful budgeting, and precise project cost tracking.
Return on investment: Estimating future requirements and the rate of technological change is essential to extending an asset's ROI.
A practical rule of thumb: If the technology is changing fast or the requirement may evaporate within a year or two, lean OpEx. If the asset is core to how you operate and you'll still need it in five years, CapEx wins.
The accounting rules look clean on paper. In practice, four mistakes show up over and over.
Some teams try to capitalize software, consulting time, or maintenance work that should be expensed. Capitalizing too aggressively inflates current earnings and creates an audit problem later. The test is whether the spend creates a new asset or extends an existing one's useful life – if it just keeps the lights on, it's OpEx.
Subscription software is almost always OpEx, but the line gets blurry on cloud implementation work. Under ASC 350-40 (as amended by ASU 2018-15), companies are required to capitalize implementation costs incurred during the application development phase of a hosting arrangement – custom configuration, coding, and system integration work – and amortize them over the term of the hosting contract. The mistake is capitalizing the wrong phases: training costs and post-go-live support must be expensed as incurred. Misclassifying those phases inflates the balance sheet and creates an audit problem later.
Check the accounting standard that applies to you (ASC 350-40 in the US for internal-use software, IFRS for international) before booking cloud spend as a capital asset. The same caution applies to AI initiatives: While building and training a proprietary model in-house might involve capitalizable internal engineering labor, the ongoing costs of running day-to-day AI queries and prompt inference are strictly operational.
Categorizing spend at the GL level isn't enough. If you can't trace CapEx and OpEx back to specific projects, you can't tell finance which initiatives are eating the budget. Project-level tracking is what turns the classification into a planning tool.
Internal engineering time spent building a capital asset can sometimes be capitalized, but most teams either miss the opportunity or capitalize hours that shouldn't qualify. Get a written policy, get finance and tax to sign off, and track those hours separately from regular operational work.
Whether you need to monitor a single CapEx initiative or keep tabs on an entire portfolio of OpEx work, Tempo Financial Manager and Structure PPM give you real-time cost visibility right inside Jira.
Use Financial Manager to track budgets, expenses, and profitability, and rely on Structure PPM for live, roll-up views of scope and schedule that keep every stakeholder informed. For teams that want forward-looking numbers, project cost forecasting inside Financial Manager combines actuals, planned work, and budget data so you see overruns coming before they hit the books.
Sign up for a demo
Request Demo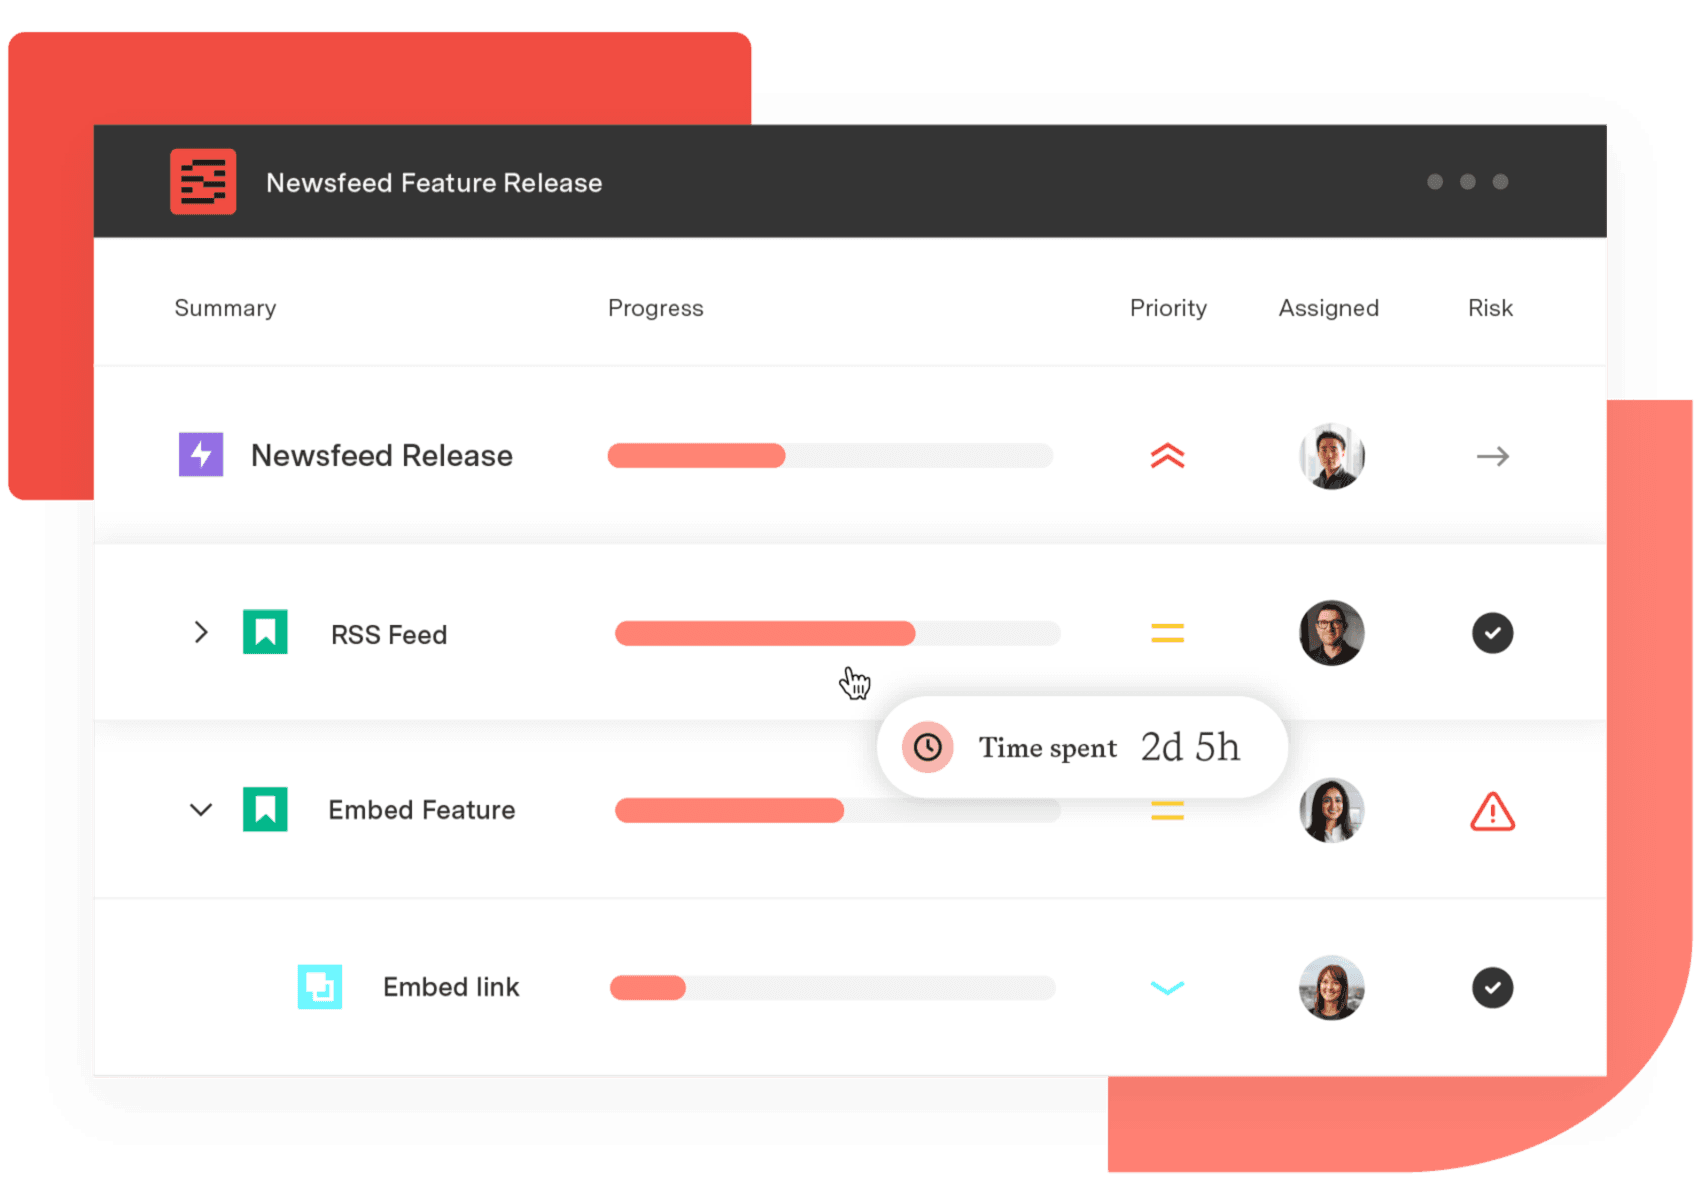
Structure PPM
Manage products, projects, and programs in a single spreadsheet-like view. By providing a clear, real-time view of project progress and resource allocation, Structure helps teams meet deadlines and adapt swiftly to changing priorities.
Start a Free TrialCouldn't find what you need?Go to our documentation
Start with the time test. If the item will help the business for more than one year, it's usually a capital expense (CapEx). If the benefit is used up within the year, it's an operational expense (OpEx). Check three things: length of benefit (multi-year for CapEx, within the year for OpEx), ownership (you own or build an asset for CapEx, pay to use or maintain something for OpEx), and accounting treatment (depreciated or amortized for CapEx, deducted right away for OpEx). If you're still not sure, consult your finance team or tax adviser. Many companies set internal cost thresholds that refine these rules and keep low-value items out of the capital asset register.
Most businesses treat a laptop as a capital expense because it's a physical asset that will be used for more than one year. The cost goes on the balance sheet and is depreciated over its useful life, typically three to five years. Many companies set a cost threshold, often around $2,500. Anything below that amount gets booked as OpEx for convenience, even if it technically meets the useful-life test. Check your internal policy before you code the purchase, and ask finance whether bulk hardware buys for a new team need to be handled differently from one-off replacements.
Employee salaries, hourly wages, and benefits are operational expenses. They keep the business running day to day and are recorded on the income statement in the period they're earned. The exception: in rare cases, labor costs that can be directly tied to building a long-term asset – like engineering hours that meet the criteria for capitalized software development – can be capitalized. Those exceptions need a written capitalization policy, tax review, and accurate time tracking against the qualifying project. Your accounting team will flag those cases during project setup.
Cloud computing has pushed a lot of what used to be CapEx into the OpEx column. Buying servers, storage, and perpetual software licenses used to mean big capital outlays followed by years of depreciation. With AWS, Azure, Google Cloud, and SaaS apps, you pay monthly or annually for the same capability, and the expense lands on the income statement as you consume it. That generally improves cash flow and lowers the bar for trying new tools, but it can also make total IT spend harder to control if no one is watching the meter. The shift also changes how investors read your balance sheet – fewer capitalized assets doesn't necessarily mean a leaner business.
There's no formal 80/20 rule in accounting standards, but the phrase usually refers to a budgeting heuristic: roughly 80% of your spend goes to OpEx (the recurring cost of keeping the business running) and 20% to CapEx (the strategic investments that change what you can do). The exact split varies wildly by industry – capital-intensive sectors like manufacturing, utilities, and telecom run heavier on CapEx, while professional services and SaaS companies skew strongly toward OpEx. The point of the heuristic is to remind leadership that most of the budget protects today's business; the smaller capital pool is what funds tomorrow's.
Yes. Tools like Tempo Financial Manager and Tempo Timesheets categorize hours and expenses by project, so finance can pull CapEx and OpEx reports without manual reclassification. Tempo Accounts tags time as capital or operating at the source, then rolls that data up for tax credit applications, cost center reporting, and ROI analysis. Pair that with Tempo Structure PPM for portfolio-level views, and the same numbers feed delivery, finance, and the board. The win isn't just compliance – it's that classification stops being an after-the-fact accounting chore and becomes part of how teams plan work.
OpEx and CapEx tracking basics can help reduce your company’s bottom line, balance project budgets, and identify cost-cutting opportunities.

Learn how incorporating a decision log into your project management process can smooth communication and build alignment behind your choices.

What are operating expenses? How does tracking them improve a company’s bottom line? Here are the basics for understanding this type of expenditure.

Learn how to draft sound financial reports to track organizational performance and make sound business decisions that safeguard the company’s future.

AI spend management software controls buying and meters usage. See the leading tools and how finance attributes AI cost to the work it produced.

Take control of technology spending by implementing an effective and practical IT financial management framework that eliminates waste & redundancies.
Take control of your business’s future by learning how financial forecasting can positively impact your balance sheet and economic evolution.

Financial oversight ensures you have the assets needed to successfully deliver project outcomes. Here’s how to establish a oversight methodology.

Explore the essential connection between project management and budgeting. Effective planning ensures successful project budgets from the start.